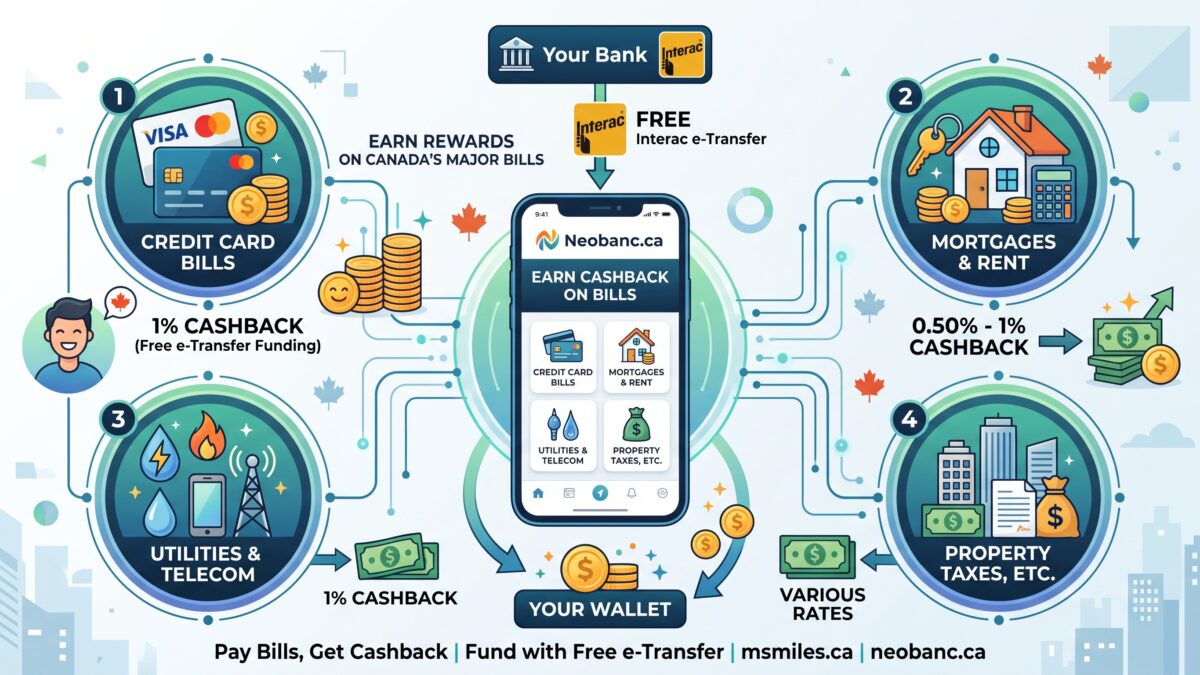
For Canadian points collectors and cashback optimizers, recurring fixed overhead—rent, mortgage installments, property taxes, and utility bills—has traditionally been the ultimate unrewarded spend. Because traditional Canadian lenders and billers rarely accept credit cards without punishing surcharges (or refuse them outright), substantial household spend slips past our reward balances every single year.
Even paying off your monthly credit card balance via online banking is typically a zero-return chore. Neobanc.ca changes that equation by allowing Canadians to monetize everyday household overhead, including earning cashback when you settle your monthly credit card statement with Interac e-Transfer.
What is Neobanc.ca?
Neobanc is a Canadian financial platform designed to reward routine household overhead. Instead of sending an Interac e-Transfer directly to a landlord or letting a mortgage payment auto-debit straight from a chequing account with zero upside, you route those scheduled payments through the Neobanc dashboard.
- Supported Bills: Credit card balances (Visa, Mastercard, American Express), mortgages, rent, property taxes, condo fees, tuition, and home utilities (hydro, gas, water, internet, mobile).
- Funding Rails: Free Interac e-Transfer or linked payment cards.
- Cashback Accrual: Earn between 0.50% and 1.00%+ cashback directly into your Neobanc wallet balance.
- Redemption Flexibility: Withdraw accrued cashback directly to your connected Canadian bank account via EFT or apply it toward future bill payments.
The Double Dip: Earning Cashback on Credit Card Bill Payments
The standout tactical opportunity for rewards enthusiasts is the ability to earn cashback when paying off your credit card balance via Interac e-Transfer.
Normally, paying a $3,500 monthly credit card balance through standard bank bill pay yields $0. By routing that statement payoff through Neobanc:
- Earn Card Rewards First: Charge your daily purchases to your favorite travel or cashback credit card to earn your standard points, miles, or card-level cashback (typically 1.5% to 5%).
- Pay the Statement via e-Transfer: Fund the credit card payoff via free Interac e-Transfer inside the Neobanc dashboard.
- Earn Neobanc Cashback on the Payoff: Earn an additional baseline 1% cashback on the bill payment itself—completely fee-free.
| Step | Action | Return / Fee | Net Gain |
|---|---|---|---|
| 1. Card Purchases | Spend $3,500 on your rewards card | Earn ~2% card rewards ($70 value) | +$70 |
| 2. Statement Payoff | Pay $3,500 card bill via Neobanc e-Transfer | 0% fee (Interac e-Transfer is free) | $0 fee |
| 3. Neobanc Cashback | Neobanc rewards payment | Earn 1% cashback ($35) | +$35 |
| Total Strategy | Combined Double Dip | ~3% effective blended return | $105 total |
On a household running $3,500 a month in card spend, this mechanism unlocks $420 per year in pure found money on payments you already make.
What Does the Annual Return Look Like?
When you combine multiple fixed expenses across a single household, the cumulative yield adds up quickly.
Here is a realistic annual projection for a Canadian household managing a $3,200 monthly mortgage, $450 in recurring monthly utilities, and $3,500 in monthly credit card spend paid off in full:
| Expense Category | Monthly Spend | Funding Method | Cashback Rate | Monthly Return | Annual Cashback |
|---|---|---|---|---|---|
| Mortgage | $3,200 | Interac e-Transfer | 0.50% | $16.00 | $192.00 |
| Utilities & Telecom | $450 | Interac e-Transfer | 1.00% | $4.50 | $54.00 |
| Credit Card Statement Payoff | $3,500 | Interac e-Transfer | 1.00% | $35.00 | $420.00 |
| Total Annual Neobanc Cash | $7,150 / mo | — | — | $55.50 / mo | $666.00 / yr |
Annual Potential by Household Spending Volume
| Monthly Mortgage | Monthly CC Payoff | Annual Mortgage Cash (0.5%) | Annual CC Cash (1.0%) | Utilities ($450/mo @ 1%) | Total Annual Neobanc Cash |
|---|---|---|---|---|---|
| $2,000 | $2,000 | $120 | $240 | $54 | $414 / yr |
| $2,500 | $3,000 | $150 | $360 | $54 | $564 / yr |
| $3,200 | $3,500 | $192 | $420 | $54 | $666 / yr |
| $4,000 | $5,000 | $240 | $600 | $54 | $894 / yr |
| $5,000 | $6,500 | $300 | $780 | $54 | $1,134 / yr |
How Neobanc Compares Across Major Living Expenses
| Expense Type | Traditional Bank Bill Pay / Direct Debit | Neobanc via Interac e-Transfer | Neobanc via Credit Card |
|---|---|---|---|
| Credit Card Bills | 0% return, $0 fee | 1% cashback, $0 fee | N/A (Card-on-card restricted) |
| Mortgages | 0% return, direct bank debit | 0.50% cashback, $0 fee | Subject to lender eligibility |
| Utilities & Telecom | 0% return, $0 fee | 1% cashback, $0 fee | Card rewards + platform cashback (1.50% fee) |
| Rent | 0% return, $0 fee | Cashback + credit reporting, $0 fee | Card rewards + platform cashback (1.50% fee) |
Best Practices and Execution Rules
- Buffer Payment Windows (3 to 5 Business Days): Credit card issuers and mortgage servicers enforce strict payment cutoffs. Always schedule and fund your transfers 3 to 5 business days ahead of the payment due date to ensure smooth settlement and avoid late penalties.
- Keep Payment Rails 100% Free: Use Interac e-Transfer for mortgage and credit card settlements so you never pay card processing surcharges, ensuring your cashback is 100% net profit.
- Test with a Small Bill First: Before routing large mortgage payments, run a smaller utility bill or modest credit card payment to verify your linked accounts, notification alerts, and processing timelines.
- Account Verification: Because Neobanc processes regulated financial transactions under Canadian MSB rules, prepare to complete basic identity verification during onboarding before unlocking full monthly limits.
Neobanc turns non-negotiable household overhead into a systematic rewards generator, making it a powerful addition to any Canadian personal finance and points optimization routine.

Leave a Reply